

Quick Answer: Are There Data Center Stocks in India?
Data center stocks in India currently offer limited pure-play listed options. The closest listed exposure is Adani Enterprises (via its AdaniConneX JV). Most major operators - Nxtra Data, Yotta, CtrlS - are unlisted. The most accessible investment angle is through IT hardware stocks in the power backup, precision cooling, and networking equipment supply chain. India's colocation capacity is projected to reach 1.7 GW by end-2026, growing at 15–20% CAGR.
Introduction
Most investors discovered data center stocks in India the wrong way — through a headline, a tip, or a sudden spike in a related counter. But if you've tried to find a clean, listed pure-play data center company on NSE and come up empty, you're not imagining things. The sector is genuinely messy to invest in from India, and that's exactly what makes it worth understanding properly.
Data centers are the physical backbone of everything running on the cloud. Every time you use ChatGPT, stream a video on JioCinema, process a UPI transaction, or retrieve a patient record from a hospital portal, a data center is doing the work. India is building a lot more of this infrastructure, fast, and the investment case for data center stocks in India flows directly from that build-out.
The challenge for Indian investors is that the best-known global data center companies, Equinix, Digital Realty, and Iron Mountain, are listed in the US. In India, the sector is mostly split between unlisted operators, conglomerate subsidiaries, and companies that benefit indirectly through IT hardware stocks and infrastructure equipment. Navigating this requires understanding how the sector is structured, not just which names are trending.
See what markets are pricing in
Live indices, sector moves and market breadth — the backdrop to every story we publish.
Why Data Center Stocks in India Are Growing: AI, Cloud & Localisation
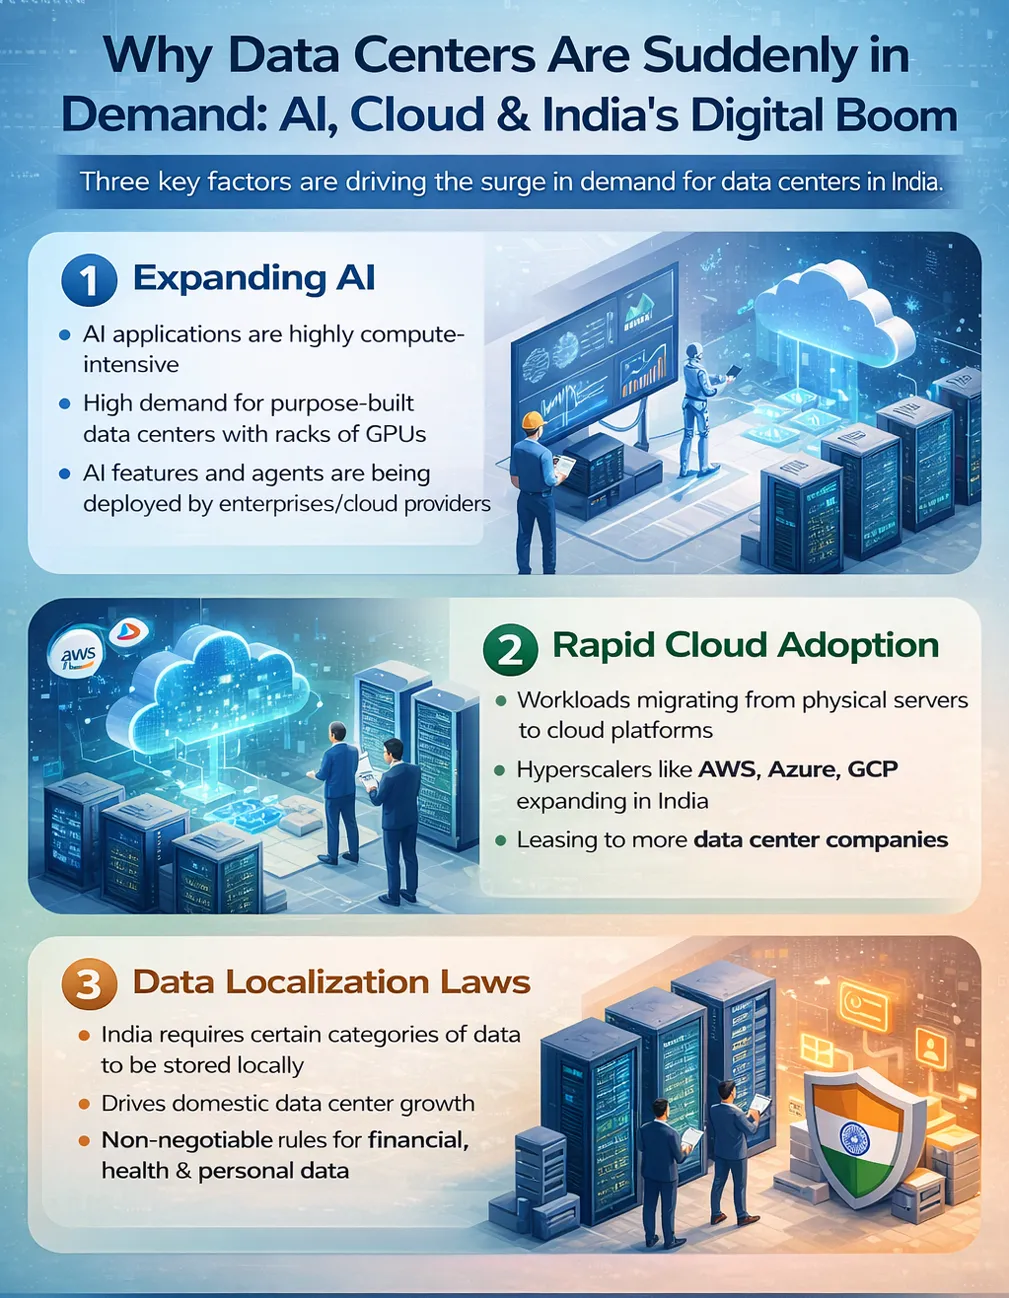
The demand story has three distinct drivers, and they are all running at the same time.
The first is AI. Large language model training and inference are the two things that make AI applications work and are extraordinarily compute-intensive. Running these workloads requires racks of GPUs operating at high utilisation rates, which in turn requires the kind of controlled, high-density computing environment that only purpose-built data centers can provide. Every AI company, every cloud provider building AI features, and every enterprise deploying AI agents needs more data center capacity.
The second driver is cloud migration. Indian enterprises, banks, insurers, manufacturers, and government departments are moving workloads off physical servers and onto cloud platforms. AWS, Azure, and GCP are all expanding their Indian regions, which means building or leasing more data center companies in India. The hyperscalers don't always build themselves; they often lease capacity from colocation operators, which creates a direct revenue opportunity for listed players.
The third driver is regulation. India's data localisation rules require certain categories of data — financial, health, and personal to be stored on servers physically located within India. That is a structural, non-negotiable tailwind for domestic data center capacity, regardless of what happens globally.
India's Data Center Market Size, Growth & Investment Hubs (2026)
India's installed data center capacity crossed 1,300 MW by the end of 2025. Industry projections put colocation capacity at 1.7 GW by the end of 2026, and some estimates have the market growing at a CAGR of 15–20% through 2030.
To put that in perspective: a decade ago, India had under 100 MW of organised colocation capacity. The scale-up has been dramatic, but the base is still low relative to the US (which has over 10,000 MW) and even Singapore. That gap is the investment thesis in one number.
The geographic concentration is important for investors tracking data center shares in India and related real estate costs. Mumbai leads, accounting for roughly 50–55% of total capacity, driven by submarine cable landings, proximity to financial services clients, and existing power infrastructure. Pune and Chennai are the next-largest hubs. Hyderabad and Noida/Greater Noida are growing fast, partly because they have better land availability and lower costs than Mumbai.
| Hub | Why it attracts data centres |
|---|---|
| Mumbai | India's largest hub, with the most subsea cable landings, financial-sector demand and the biggest investments by global and Indian operators |
| Chennai | Second major cable-landing hub, strong power supply and lower land costs |
| Hyderabad | Reliable power, supportive state policies, and demand from cloud and tech companies |
| Delhi-NCR | Large enterprise and government demand, strong fibre connectivity across north India |
| Pune | Close to Mumbai for backup and disaster recovery, with lower land and power costs |
These hubs grow where four things come together: connectivity (subsea cables and fibre), reliable, affordable power (increasingly renewable), enterprise and cloud demand, and infrastructure investment backed by state incentives.
Investment hubs and their primary characteristics:
City | Capacity Share | Key Drivers | Land/Power Status |
Mumbai | ~50–55% | Finance, submarine cables | Constrained, high cost |
Pune | ~12% | Manufacturing, BPO, overflow | Growing availability |
Chennai | ~10% | IT exports, southern corridor | Competitive costs |
Hyderabad | ~8% | GCCs, pharma, IT | Lower land costs |
Noida/NCR | ~7% | Government, telco, North India | Expanding fast |
Bengaluru | ~8% | Tech startups, GCCs | Power constraints |
Major Data Centre Hubs in India: Mumbai, Chennai, Hyderabad, Delhi-NCR and Pune
Mumbai leads India’s data centre market with 890 MW of operational capacity, about half the national total, thanks to its subsea cables, reliable power and BFSI demand. Chennai (214 MW) also benefits from subsea connectivity, and Delhi-NCR (183 MW) grows on cloud and government demand. Hyderabad (151 MW) has the second-largest pipeline, driven by hyperscaler and AI investment, while Pune (133 MW) attracts hyperscalers with affordable land.
Data Center Policy, Tax Incentives and Data Localisation in India
Measure Status Infrastructure status for data centres above 5 MW (cheaper long-term credit) Implemented (2022) Tax holiday till 2047 for foreign cloud firms serving global customers from Indian data centres Announced in Budget 2026–27; applies only to companies the government notifies National Data Centre Policy (single-window clearances, incentives) Still a draft DPDP data rules: no blanket localisation, transfers allowed except to restricted countries Rules notified Nov 2025; cross-border provisions start May 2027 Sector rules such as RBI’s payment data localisation In force State policies: Telangana, Maharashtra, Tamil Nadu, plus new UP and Gujarat policies (2026) offering power, land and subsidy incentives In force
How to Categorise Data Center Stocks in India: Pure-Play vs Indirect Beneficiaries
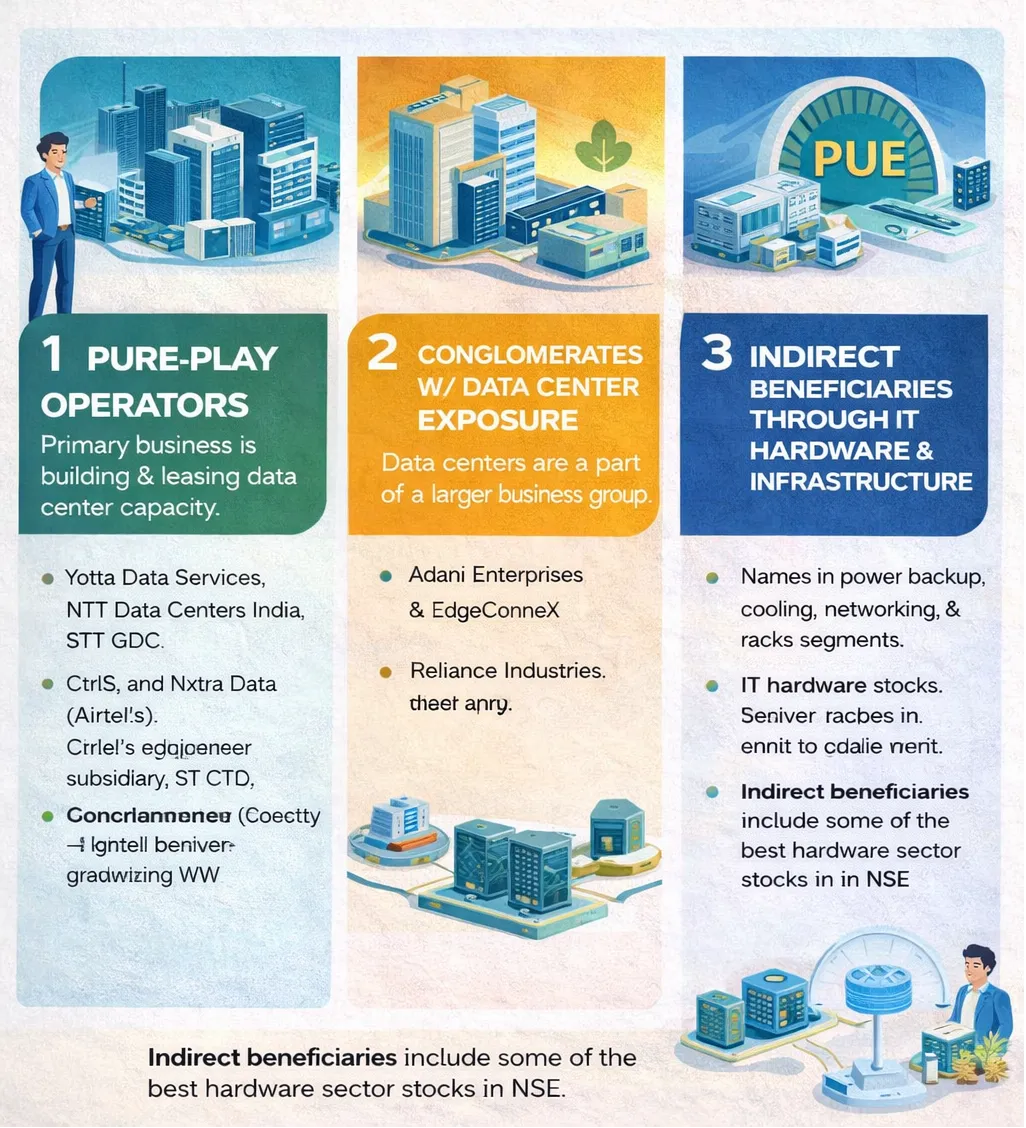
This is the most important framing for any investor looking at data centre stocks in India. There are essentially three buckets:
Bucket 1 — Pure-play operators. These are companies whose primary business is building and leasing data center capacity. Most of the major Indian operators are currently unlisted: Yotta Data Services, NTT Data Centers India, STT GDC (ST Telemedia), CtrlS, and Nxtra Data (Airtel's data center subsidiary, which has filed DRHP for an IPO). If Nxtra and Yotta are listed, they would be the closest thing to a direct pure-play investment available to Indian retail investors.
Bucket 2 — Listed conglomerates with data center exposure. Adani Enterprises has made the most public commitment to the data center space through its joint venture with EdgeConneX. This doesn't make Adani Enterprises a data center stock, but it does mean a slice of the conglomerate's forward growth is tied to data center capex. Similarly, Reliance Industries has significant digital infrastructure ambitions. Investors buying these for data center exposure are also buying the rest of the business, both the upside and the complexity.
Bucket 3 — Indirect beneficiaries through IT hardware and infrastructure. Companies making or supplying IT hardware stocks power backup systems, cooling equipment, server racks, cable management, and networking equipment, benefit from every data center that gets built, regardless of who owns it. This is where some of the most investable listed opportunities currently sit among the top 20 hardware sector stocks in India and hardware sector stocks in NSE.
Data Center Companies in India: Listed & Unlisted Players
Adani Enterprises is the most prominent listed name linked to data center companies' stocks in India. Through AdaniConneX, the JV with EdgeConneX, it is developing hyperscale data center campuses in Mumbai, Chennai, Noida, Hyderabad, and Pune. The JV has announced a target of 1 GW of capacity. That is a large commitment, and the revenue impact will show up in Adani Enterprises' consolidated financials as assets commission over the next three to five years.
Nxtra Data (Airtel subsidiary) operates 10 large and 120 edge data centers. Its filed DRHP is one of the most closely watched potential IPOs in the infrastructure space. If it lists, it would give Indian investors a relatively clean exposure to the colocation market.
Yotta Data Services (Hiranandani group) operates one of India's largest campuses in Navi Mumbai and has expansion plans. Currently unlisted.
On the IT software stocks and cloud services side, companies like TCS, Infosys, and Wipro benefit indirectly, as they sell managed services and cloud migration work to enterprises building or leasing data center capacity, but they are not data center operators themselves. Distinguishing between IT software stocks and software IT sector stocks on the one side and capital-heavy data center infrastructure companies on the other is important for valuation purposes; the two have very different capital intensity profiles.
IT Hardware Stocks and the Supply Chain Opportunity
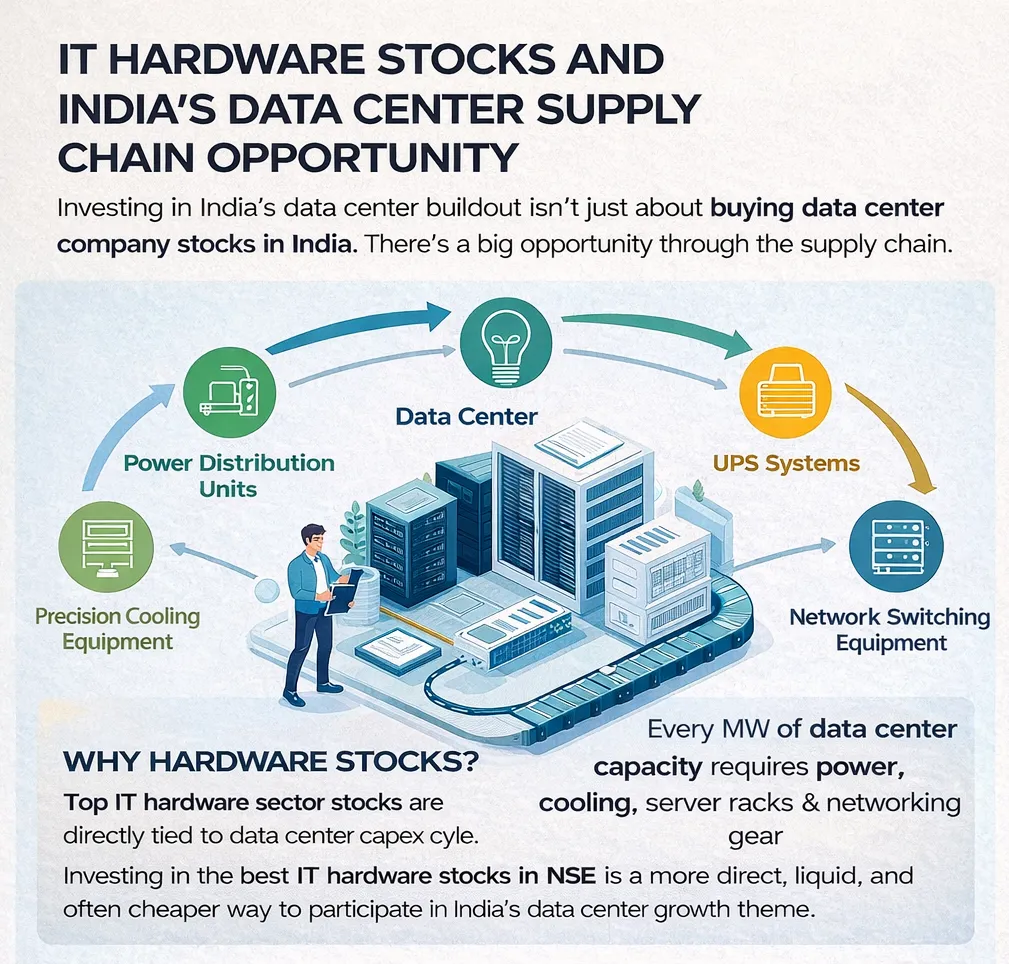
Here's a view that often gets missed: some of the most accessible ways to invest in India's data center buildout are not through data center companies' stocks in India directly, but through the supply chain.
Every MW of data center capacity requires power distribution units, UPS systems, precision cooling, server racks, and network switching equipment. The companies making and distributing this equipment are listed, liquid, and directly tied to the capex cycle of top data center companies in India.
When looking at the top 10 hardware sector stocks in India or the broader universe of top 20 hardware sector stocks in India, the relevant filters for data center exposure are: does this company supply power infrastructure, cooling systems, or networking gear to hyperscale or colocation data centers? Companies in the best IT hardware stocks universe with strong order books from data center clients are a more direct and often cheaper way to participate in the theme than buying a conglomerate at a premium.
Among hardware sector stocks in NSE, names in the power backup (UPS, inverters) and precision cooling segments have seen order inflows from data center customers grow meaningfully over 2024–2026. This is worth tracking in quarterly result commentary, even if the headline business category doesn't say "data center."
Data Center Policy, Tax Incentives and Data Localisation in India
Data Center Cooling Stocks in India: HVAC and Thermal Management
Servers produce intense heat, so data centres need chillers, precision HVAC, MEP systems and, increasingly, liquid cooling for AI chips. Cooling is one of the biggest operating costs.
| Company | Confirmed data centre exposure |
|---|---|
| Blue Star | About ₹1,000 crore data centre MEP revenue in FY26; targets about 20% of revenue by FY29 |
| Voltas | New data centre vertical with about ₹200 crore of orders so far |
| Navin Fluorine | Liquid cooling fluid partnership with Chemours; early stage |
| Aeroflex Industries | Reported coolant distribution unit supplier for Vertiv (verify with filings) |
Get research like this in your inbox
The week’s research that mattered, in five minutes. Joined by 2L+ investors.
How to Evaluate Data Center Stocks in India: Power, Utilisation & Capex
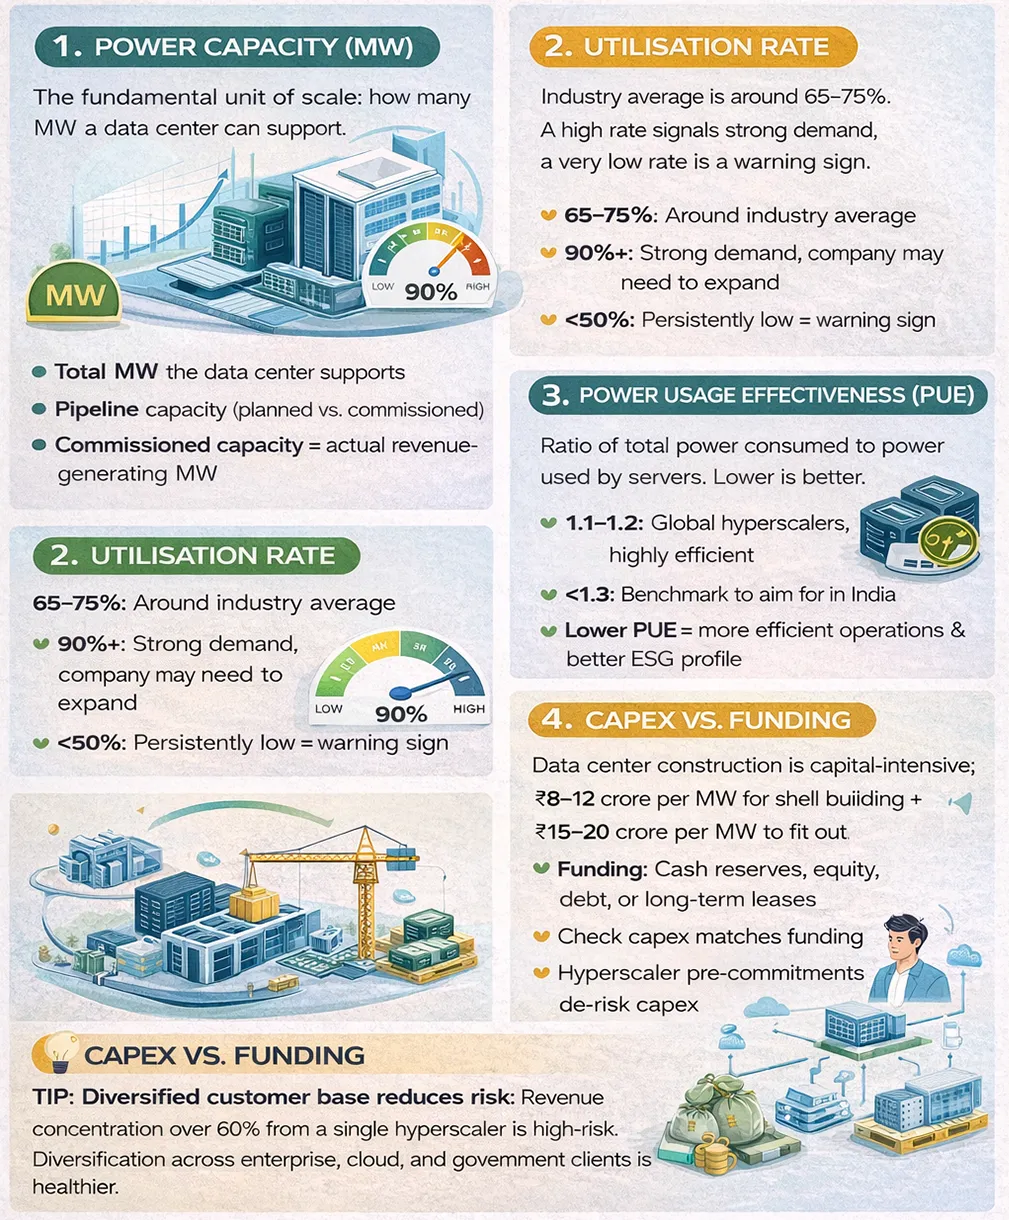
For the few listed companies with meaningful best data center stocks exposure, and for the upcoming IPOs, here are the metrics that matter:
Power capacity (MW): The fundamental unit of scale. A data center is valued partly on how many MW it can support. Pipeline capacity (announced but not yet commissioned) matters for growth, but only commissioned capacity generates revenue.
Utilisation rate: Industry average is around 65–75%. A high utilisation rate close to 90%+ signals strong demand but also means the company needs to build more capacity, or it will cap its own growth. A very low utilisation rate on new capacity is normal in year one; persistently low rates are a warning sign.
Power Usage Effectiveness (PUE): The ratio of total power consumed to power used by computing equipment. A PUE of 1.3 means that for every 1W used by servers, 0.3W is overhead (cooling, lighting). Lower is better. Global hyperscale data centers run at 1.1–1.2. Older Indian facilities are higher. Improving PUE is both a cost efficiency story and an ESG story.
Capex commitment vs. funding: Data center construction is capital-intensive, roughly ₹8–12 crore per MW for shell construction, plus another ₹15–20 crore per MW for fit-out. Check whether capex is funded through equity, debt, or long-term lease agreements with hyperscaler clients. Hyperscaler pre-commitment de-risks capex significantly.
Customer concentration: A data center with 80% revenue from one hyperscaler is high-risk if that client renegotiates or builds its own facility. Diversification across enterprise, cloud, and government clients is healthier.
Financial Metrics to Compare: Market Cap, P/E, ROCE, Debt and Returns
Compare data centre stocks on market cap (size), P/E (valuation vs growth), ROE/ROCE (above about 15% is healthy), debt-to-equity (below about 1), sales growth (steady over 3–5 years) and returns (over the same periods).
| Company | Data Centre Link | Market Cap (₹ cr) | P/E | ROCE | D/E | 1Y Return |
|---|---|---|---|---|---|---|
| L&T | Construction | 4,99,051 | 31.0 | 16.5% | 0.98 | −6.9% |
| ABB India | Electrical equipment | 1,44,119 | 86.4 | 28.5% | 0.01 | +18.5% |
| Cummins India | Backup power | 1,27,734 | 54.1 | 35.0% | 0.00 | +6.6% |
| Blue Star | Cooling and MEP | 32,229 | 61.1 | 21.0% | 0.24 | −24.0% |
| Voltas | Cooling and MEP | 34,051 | 90.6 | 9.3% | 0.16 | −33.6% |
| Anant Raj | Data centre developer | 18,417 | 33.2 | 10.4% | 0.12 | −26.6% |
Key Risks: Power Costs, Capacity Utilisation, Capex and Technology
- High capex: Heavy upfront spending, often debt-funded, delays returns.
- Power costs: Rising electricity tariffs or unreliable supply squeeze margins.
- Slow utilisation: Unleased capacity keeps costs high while revenue lags.
- Technology obsolescence: AI workloads may force costly cooling and power upgrades.
- Contract risks: Dependence on a few large customers makes earnings vulnerable to lost or repriced contracts.
Best Data Center Stocks in India: Top Listed Companies and Share Prices
Data Centre Stocks in India with Price, Market Cap and Financial Metrics
| Company | Type | Exposure | Price (₹) | Market Cap (₹ cr) | P/E | ROCE | 1Y Return |
|---|---|---|---|---|---|---|---|
| Anant Raj | Direct | Converting IT parks to data centres | 460 | 18,417 | 33.2 | 10.4% | −26.6% |
| RailTel | Direct | Data centre and telecom services | 229 | 8,197 | 23.7 | 18.6% | −38.1% |
| L&T | Indirect | Data centre construction | 3,647 | 4,99,051 | 31.0 | 16.5% | −6.9% |
| ABB India | Indirect | Electrical equipment | 6,140 | 1,44,119 | 86.4 | 28.5% | +18.5% |
| Cummins India | Indirect | Backup power | 4,344 | 1,27,734 | 54.1 | 35.0% | +6.6% |
| Blue Star | Indirect | Cooling and MEP | 1,499 | 32,229 | 61.1 | 21.0% | −24.0% |
| Voltas | Indirect | Cooling and MEP | 950 | 34,051 | 90.6 | 9.3% | −33.6% |
AI Data Center Stocks in India: Cloud, Servers and GPU Infrastructure
AI workloads need large GPU clusters, more power and better cooling, which drives demand for GPU cloud, AI servers and high-density data centres.
- Netweb Technologies makes AI servers and HPC systems. AI systems were about 62% of revenue in Q1 FY27, and its order book stood at ₹2,507 crore. It’s a hardware maker, not a data centre operator.
- E2E Networks rents GPU cloud capacity (about 5,100 GPUs) from data centres in Noida and Chennai, including IndiaAI Mission contracts. It posted a ₹72.7 crore profit in Q2 FY27. It’s a GPU cloud provider, not a pure-play operator.
Risk: Both depend on GPU supply, large orders and AI demand.
Risks of Investing in Data Center Stocks in India
No investment story in this space is complete without a serious look at execution risk.
Power availability is the single biggest constraint for data center companies in India. A large data center campus at scale consumes as much power as a small city. Getting reliable, uninterrupted power at reasonable cost and at scale in India requires either being located near power substations with dedicated feeders or investing in captive generation and renewable procurement. Power agreements that lock in cost are a competitive advantage. Power uncertainty is an operational and financial risk that can delay commissions and inflate costs.
Land acquisition in key markets, particularly Mumbai and Hyderabad, is constrained and expensive. Data centers need large floor plates, proximity to trunk fiber routes, and acceptable seismic and flood risk profiles. As more operators compete for the same sites, land costs are rising faster than capacity costs, which compresses margins on new builds.
Global competition is a structural risk that Indian operators face at the high end. Singapore, Malaysia, and the UAE are all building data center capacity aggressively and may capture cloud workloads that would otherwise have come to India. India's data localisation rules provide some protection, but the regulatory environment is not static.
Currency and import dependency for equipment, particularly for servers, GPUs, and networking gear, means that a weaker rupee inflates capex. Many data center-related stocks in India in the equipment supply chain also face import dependencies that introduce currency risk.
Best IT Infrastructure & Data Center Stocks in India: Listed & Related Stocks
Category | Name | Listed? | Key Angle |
Conglomerate with DC exposure | Adani Enterprises | Yes (NSE/BSE) | AdaniConneX JV, hyperscale pipeline |
DC IPO pipeline | Nxtra Data (Airtel) | DRHP filed | Pure-play colocation, 130+ facilities |
Telecom infrastructure | Indus Towers | Yes | Edge infrastructure, tower-to-edge play |
IT hardware stocks | Avalon Technologies | Yes | PCB assemblies for data infra |
Power backup/UPS | Luminous/Schneider-listed | Various | UPS, power distribution units |
Network equipment | Sterlite Technologies | Yes | Fiber, network infra for DCs |
IT software stocks (cloud beneficiary) | TCS, HCL Tech | Yes | Cloud migration, managed DC services |
Among the top 5 hardware sector stocks in India , most linked to data center growth, the names worth watching are in the power electronics, precision cooling, and structured cabling segments, where order books have started reflecting data center capex directly. Check management commentary in Q3 and Q4 FY26 results for explicit mentions of data center customer orders.
For investors interested in the best data center stocks available on Indian exchanges today, the honest answer is that the listed universe is thin and concentrated in conglomerates. The most direct opportunity may arrive with the Nxtra IPO and whatever follows in its wake.
Also Read: Indian Real Estate Market Trends 2026: What Investors Need to Know
Conclusion
India's data center story is real, large, and accelerating. The demand drivers for AI workloads, cloud migration, and data localisation are not going away. What's missing, for now, is a clean listed investment vehicle that gives investors pure-play exposure the way a US-listed REIT or a Digital Realty does for American investors, whether through direct stocks, a PMS with a technology infrastructure tilt
The practical approach is to understand the full value chain: the operators (largely unlisted, watch IPO filings), the listed conglomerates with data center commitments (Adani Enterprises being the largest), and the equipment supply chain it's hardware stocks, best IT hardware stocks, and hardware sector stocks in NSE where the capex cycle shows up in order books and revenue before it shows up in operator profit margins.
If you're an investor looking to position a portfolio around India's infrastructure buildout, whether through direct stocks, a PMS with a technology infrastructure tilt, or a thematic Smallcase understanding the data center sector at this level of specificity is what separates informed allocation from narrative-chasing.
Investments are subject to market risk. Please read all scheme-related documents carefully. Past performance is not indicative of future results. Wright Research & Capital Pvt. Ltd. is a SEBI-registered Portfolio Manager (Reg. No. INP000007979).
Is your portfolio built for what’s coming?
Get a free AI-powered review of your holdings — risk, overlap and quality in minutes.
Frequently Asked Questions About Data Center Stocks in India
1. What are data center stocks in India?
Data center stocks in India are equities linked to companies that build, operate, or supply data center infrastructure. Currently, most pure-play operators are unlisted. Listed exposure comes primarily through conglomerates like Adani Enterprises (via AdaniConneX) and through the equipment supply chain, IT hardware stocks in power, cooling, and networking.
2. Which are the top data center companies in India?
The top data center companies in India by capacity are Adani Enterprises (through AdaniConneX), NTT Data Centers India, Nxtra Data (Airtel subsidiary), CtrlS, Yotta Data Services, and STT GDC. Of these, only Adani Enterprises is currently listed. Nxtra has filed a DRHP for an IPO.
3. What are data center-related stocks in India that are listed on NSE?
Data center-related stocks in India listed on NSE include Adani Enterprises (operator level), Sterlite Technologies (fiber/network), Indus Towers (edge infrastructure), and select hardware sector stocks in NSE in the power electronics and cooling segments. The pure-play listed universe is currently thin.
4. What is the difference between IT hardware stocks and software IT sector stocks?
IT hardware stocks refer to companies making physical infrastructure servers, UPS, networking gear, PCBs, cables, and cooling systems. Software IT sector stocks are companies selling software services, cloud, and IT consulting. Data center exposure is primarily a hardware capex story, though software IT sector stocks benefit indirectly through cloud migration and managed services contracts.
5. What are the best IT hardware stocks linked to India's data center buildout?
The best IT hardware stocks for data center exposure are generally found in three categories: power backup and UPS manufacturers, precision cooling equipment suppliers, and structured cabling and fiber companies. Look for quarterly results where management explicitly mentions data center clients as a growing order source.
6. When will Nxtra Data IPO list on NSE?
Nxtra Data (Airtel's data center subsidiary) has filed its DRHP with SEBI. A listing date has not been announced as of early 2026. Once listed, it would be among the closest to a pure-play data center stock opportunity available to Indian retail investors on NSE.
7. How large is India's data center market in 2026?
India's colocation capacity is projected to reach 1.7 GW by the end of 2026, up from approximately 1,300 MW at the end of 2025. The market is growing at a CAGR of 15–20%, driven by AI adoption, cloud migration, and data localisation regulations.
8. What Factors Affect Data Center Stock Prices?
Data centre stocks move with AI and cloud demand, since faster adoption raises demand for capacity and leasing. Hyperscaler partnerships, such as long-term contracts with Microsoft, AWS or Google, can lift sentiment by securing future revenue. In the other direction, heavy capital expenditure, rising power costs and weak financial results can weigh on prices. Policy changes also matter, such as data localisation rules, state incentives and power tariffs.


